Collecting Cross‑Market Live Market Data: Fetch A‑Share, Hong Kong and US Real‑Time Quotes via Python WebSocket
Abstract For cross‑market quantitative research and financial tech prototyping, developers often need to monitor real‑time order‑book data from A‑Share, Hong Kong and US equity markets. Manually switching among multiple market clients brings human‑induced observation latency, and raw market data can
Building 1‑Minute K‑Lines From Tick Data: Handling Cross‑Minute Trades and Duplicate Packets
Introduction In algorithmic and quantitative research, 1‑minute K‑lines (OHLCV candles) form one of the most widely‑used datasets for factor mining, strategy backtesting and simulation validation. There are two common approaches to obtain 1‑minute candles. The first is to call ready‑made candle endp
Working with a Real‑Time Forex API: Stream Currency‑Pair Ticks Using Python WebSocket
Tags: #Python #WebSocket #ForexAPI #QuantTrading #Backtesting Summary: Reliable tick‑level market data is fundamental for forex strategy backtesting and algorithmic research. This article compares HTTP polling and WebSocket streaming, shares runnable Python implementation, and outlines key practical
A Practical Guide to Fixing Duplicate Tick Data in HK Real-Time API
Introduction When building quantitative trading systems, market data collectors, and running strategy backtests for Hong Kong stocks, most traders encounter a tricky yet overlooked problem: their calculated volume metrics, tick-based indicators, and candlestick charts never fully match official exch
Real‑Time US Stock Dashboards: What API Fields Do You Actually Need?
Tags: #QuantDevelopment #USStocks #MarketAPI #WebSocket #Python For quantitative traders and strategy researchers, a real‑time US stock dashboard is more than a visualization tool. It serves for live strategy observation, signal verification, and raw tick‑data collection for future backtesting. Many
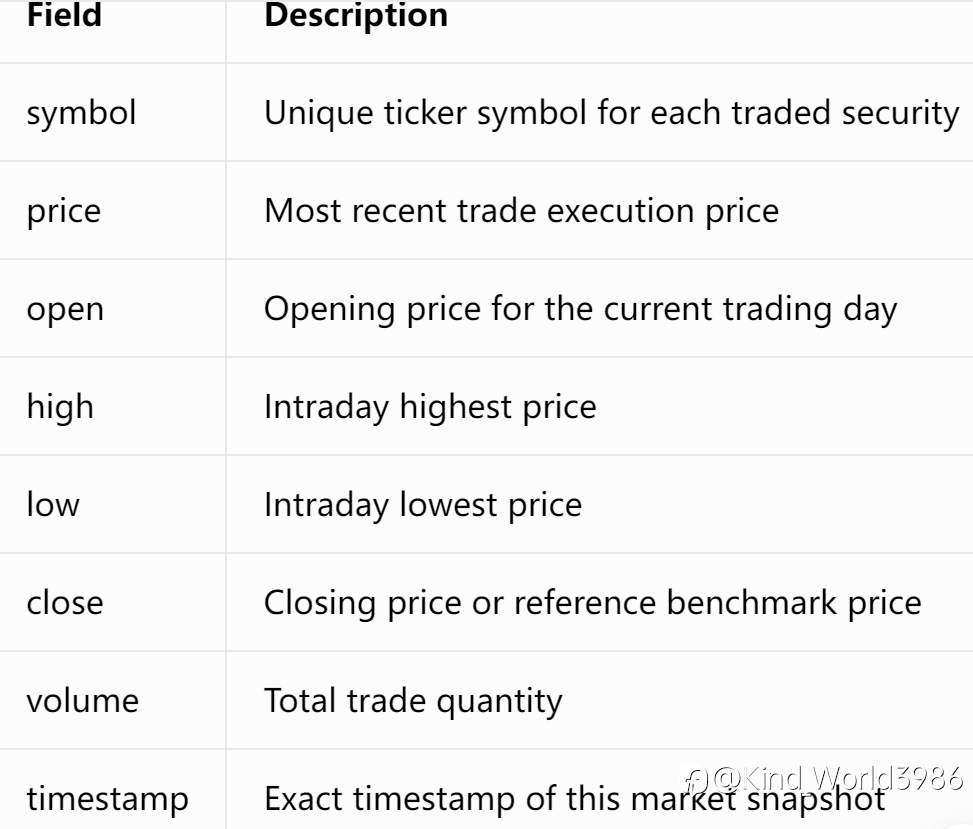
Building a Real‑Time US Stock Dashboard: API Field Selection & Practical Quant Notes
Tags: #QuantDevelopment #USStocks #MarketAPI #WebSocket #Python For quantitative traders and strategy researchers, a real‑time US stock dashboard is more than a visualization tool. It serves for live strategy observation, signal verification, and raw tick‑data collection for future backtesting. Many
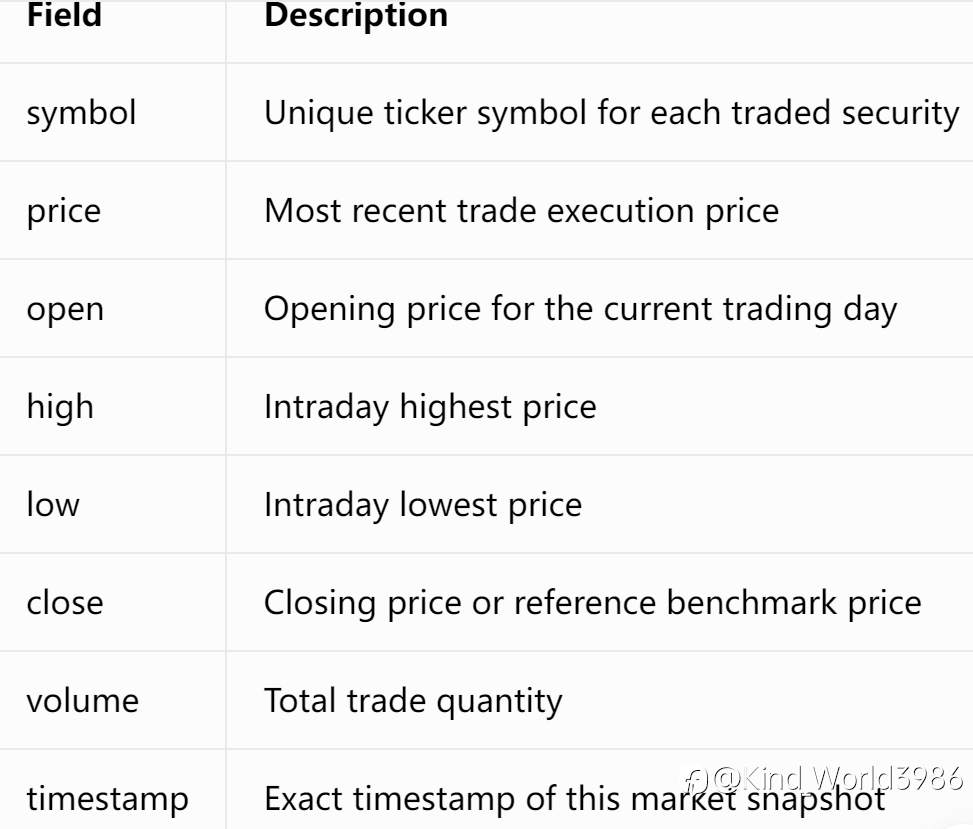
How to Resolve Suspended Stock Time-Series Gaps When Backtesting Daily Data With Free Market APIs
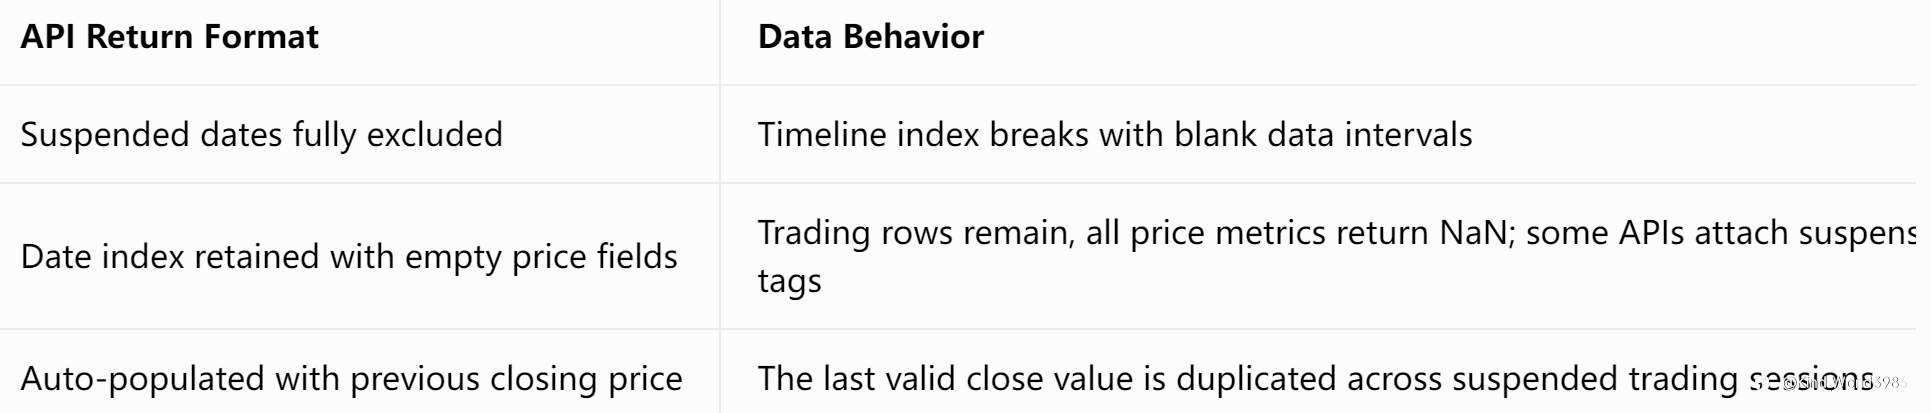
Introduction Quantitative traders and strategy researchers often leverage free stock market APIs to retrieve daily OHLC historical data for offline backtesting, effectively cutting down data procurement costs and accelerating model iteration. Yet repeated backtesting validation reveals a pervasive d