


MACRO ECONOMIC CALENDAR
Weekly Economic Calendar: Week of 21 – 25 September 2026
Followme News Desk | September 21, 2026 | All times GMT+8
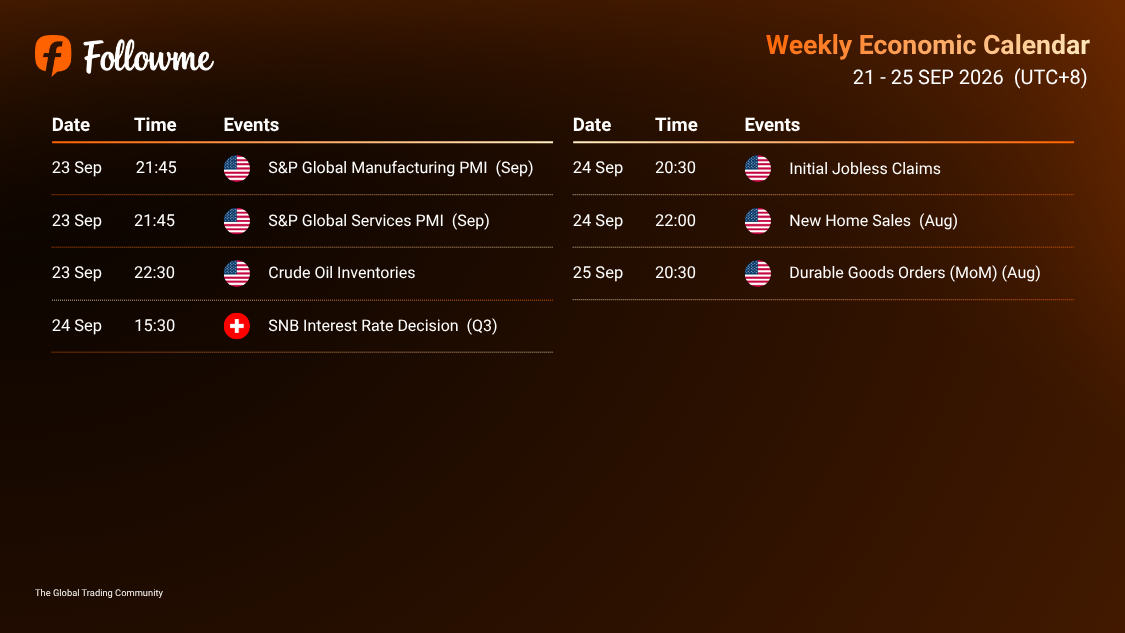
This week's economic calendar is focused on U.S. S&P Global Manufacturing and Services PMI, Crude Oil Inventories, the SNB Interest Rate Decision, U.S. Initial Jobless Claims, New Home Sales and Durable Goods Orders (MoM). It's a quieter week than last by a significant margin, but the data still matters. Wednesday opens with both PMI readings alongside Crude Oil Inventories, Thursday carries the SNB, Claims and New Home Sales, and Friday closes with Durable Goods Orders.
The Services PMI is the standout event of the week. With the forecast jumping to 56.8 from 54.6, Wednesday's reading will be the first major data point to tell markets how the economy is behaving in the immediate aftermath of last week's Fed decision and dot plot. A strong Services PMI would suggest the economy is holding up better than the softening labour and housing data implied. A mistake would do the opposite, and in a week without a major central bank decision to absorb the reaction, the PMI data carries more weight than it typically would.
Key Events This Week
🕐 All times shown are GMT+8
| Date | Time | CCY | Event | Forecast | Previous |
|---|---|---|---|---|---|
| 23/9 | 21:45 | 🇺🇸 USD | S&P Global Manufacturing PMI (Sep) | 53.2 | 53.9 |
| 21:45 | ⭐ 🇺🇸 USD | S&P Global Services PMI (Sep) | 56.8 | 54.6 | |
| 22:30 | 🇺🇸 USD | Crude Oil Inventories | -1.600M | — | |
| 24/9 | 15:30 | 🇨🇭 CHF | SNB Interest Rate Decision (Q3) | 0.00% | 0.00% |
| 20:30 | 🇺🇸 USD | Initial Jobless Claims | 207K | 206K | |
| 22:00 | 🇺🇸 USD | New Home Sales (Aug) | 620K | 678K | |
| 25/9 | 20:30 | 🇺🇸 USD | Durable Goods Orders (MoM) (Aug) | 0.40% | 0.30% |
Macro Analysis
🇺🇸 U.S. S&P Global Manufacturing PMI
S&P Global Manufacturing PMI for September is forecast at 53.2, easing from 53.9 prior a pullback but still comfortably in expansion. The direction matters more than the level here. After several months of building momentum in manufacturing, a reading that slips even marginally could prompt questions about whether the sector is losing steam heading into year-end. A reading at or above 53.9 that defies the expected pullback would be the more interesting outcome and would signal that industrial activity is holding up better than forecast. A sharper drop toward 52 or below would add an early-week layer of concern that colours how Thursday's data gets interpreted.
🇺🇸 U.S. S&P Global Services PMI
S&P Global Services PMI for September is forecast at 56.8, a notable jump from 54.6 prior. That's a meaningful move if confirmed. It would suggest that the services sector has genuinely accelerated after last week's Fed decision and whatever shift in rate expectations followed. A reading at or above 56.8 would be one of the strongest services PMI prints in recent months and would push back on the narrative of a uniformly slowing economy. A miss that keeps the number closer to 54.6 or below would suggest the forecast was too optimistic, and combined with a softer Manufacturing PMI, would add to the week's cautious tone heading into Thursday.
🇺🇸 U.S. Crude Oil Inventories
Crude Oil Inventories are forecast at -1.600M, a smaller drawdown than the prior reading. A continued drawdown, even at a reduced pace, keeps the energy picture broadly supportive of oil prices. In a week where the data is relatively light compared to last Thursday's Fed-dominated session, an unexpected result in either direction could have an outsized effect on energy-related pairs and broader risk sentiment. A surprise build particularly after weeks of consistent drawdowns would be the more disruptive outcome and could weigh on oil prices heading into a session where risk appetite is already being tested by PMI data.
🇨🇭 SNB Interest Rate Decision and CHF Outlook
The Swiss National Bank is expected to hold at 0.00% for Q3, unchanged from the prior meeting. Switzerland has been running at or near zero rates for some time, and the SNB rarely surprises. What matters here is any signal about the direction of monetary policy in the context of a global environment where major central banks are starting to discuss cuts. A hold with neutral language would be broadly CHF-neutral and largely ignored by broader markets. Any unexpected language about the franc's valuation or inflation trajectory could generate a sharper CHF move, but this is unlikely to be the week's dominant story for most traders.
🇺🇸 U.S. Initial Jobless Claims
Claims are forecast at 207K, ticking up from 206K prior essentially no change. After last week's soft NFP and everything that followed from the Fed decision, claims serve as a near-real-time check on whether the labour market is still holding. A reading at or below 207K would provide some reassurance that layoffs haven't accelerated in the aftermath of recent data softness. A jump meaningfully above 210K would be harder to dismiss, coming in the same week as softer PMIs and a declining housing number. It would add to the picture of an economy that's losing altitude on multiple fronts simultaneously.
🇺🇸 U.S. New Home Sales and Housing Demand
New Home Sales for August are forecast at 620K, a notable pullback from 678K prior. That's a drop of nearly 60K, a meaningful deceleration that would suggest buyer activity cooled significantly in August despite the shift in rate expectations. If confirmed, it would raise questions about whether lower mortgage rate forecasts are actually translating into demand yet, or whether the lag is longer than the market anticipated. A beat that holds closer to 678K would be reassuring and signal that buyers are returning faster than feared. A miss further below 620K would add to the week's softening economic narrative and weigh on USD heading into Friday.
🇺🇸 U.S. Durable Goods Orders
Durable Goods Orders for August are forecast at 0.40%, building slightly on 0.30% prior. A modest sequential improvement in a series that's been recovering from its July low, nothing dramatic, but directionally positive. A reading at or above 0.40% would suggest business investment is continuing to recover at a measured pace and gives USD a quiet close to the week. A mistake that pulls the number back toward flat or negative would introduce fresh concern about capital expenditure momentum at a time when consumer data and housing are both showing signs of softening. In a week without a major central bank event, this becomes one of the more important USD signals of the week by default.
Speculative Outlook for USD Traders
This is a step down from last week's intensity, but that doesn't mean it's quiet. The week opens on Wednesday with PMI data that will be read directly through the lens of whatever the Fed said on Thursday. Markets are still processing that. A Services PMI that jumps to 56.8 would suggest the economy is absorbing the rate outlook shift better than feared, which could give USD some support after what may have been a difficult week. A set of PMI readings that disappoints would reinforce the case for earlier Fed cuts and keep USD under pressure.
Thursday's session carries the SNB, Claims and New Home Sales none individually market-moving, but together they build the week's growth picture. The SNB hold adds little beyond confirming Switzerland stays on hold. Claims and New Home Sales are the more important reads if both come in soft, it adds to the momentum of a cooling economy narrative that Friday's Durable Goods can either confirm or push back against. In a week where there's no Fed speaker or major inflation print anchor positioning, the data itself sets the direction, and small misses can carry more weight than usual.
🟢 Bullish USD Scenario — Stronger Dollar Case
- Services PMI Delivers on 56.8 Forecast — A genuine surge in services activity on Wednesday would be hard to dismiss and would signal the economy is resilient even as manufacturing softens.
- Manufacturing PMI Holds Near 53.9 — A reading that defies the expected pullback would show industrial momentum is intact and add a constructive early-week tone for USD.
- New Home Sales Hold Near 678K — A much smaller decline than forecast would suggest buyers are already responding to lower rate expectations and pushing back on the housing slowdown narrative.
- Durable Goods Orders Beat 0.40% on Friday — A stronger-than-expected capital expenditure reading would provide a clean positive to close the week and support USD into the weekend.
- Claims Stay Below 207K on Thursday — Contained jobless claims in the same session as housing data would remove one bearish signal and keep the labour market story from deteriorating further.
- SNB Holds with Hawkish Tone — An unexpectedly firm SNB statement would support CHF and potentially set a cautious central bank tone that benefits risk-off sentiment and gives USD a quiet lift.
🟡 Wild Cards — High Whipsaw Risk
- PMI Surges While Manufacturing Slips — A wide divergence between the two PMI readings on Wednesday would make it genuinely difficult to read the overall economic picture, and USD could swing in both directions as the market debates which number tells the more accurate story.
- New Home Sales Miss by More Than Expected — A reading well below 620K would be an outlier large enough to move markets on its own, and in a data-light week it could dominate the Thursday session in a way that amplifies any bearish USD positioning.
- Oil Inventory Build Surprises — An unexpected crude build after weeks of drawdowns could shift energy sector sentiment quickly and create cross-market ripples that affect risk appetite and USD pairs beyond what the data alone would suggest.
- SNB Surprise Language — Any unexpected shift in the SNB's language about the franc or inflation trajectory could generate an outsized CHF move in a week where the calendar is otherwise quiet enough for smaller stories to get amplified.
- Durable Goods Miss After Soft Housing — If Friday's Durable Goods reading disappoints after a weak New Home Sales number on Thursday, the two consecutive soft prints would be difficult for USD to shake heading into the following week.
- PMI Data Directly Challenges Fed Narrative — If Services PMI misses badly and Manufacturing also softens, it would challenge the idea that the economy can absorb the current rate environment, and USD would feel the full weight of that concern.
🔴 Bearish USD Scenario — Weaker Dollar Case
- Services PMI Disappoints Below 54.6 — A reading that fails to deliver on the 56.8 forecast and falls below last month's prior would be an immediate bearish USD signal, suggesting the services rebound isn't materialising.
- New Home Sales Fall Well Below 620K — A housing number materially below forecast would add consumer sector weakness to an already softening economic picture and weigh USD into Friday.
- Claims Jump Above 210K on Thursday — A clear deterioration in claims after recent soft NFP data would revive labour market concerns and compound any bearish USD narrative from the PMI and housing data earlier in the week.
- Durable Goods Miss on Friday — A below-forecast capital expenditure reading would leave the week closing on a soft note for USD, with no major data point able to rescue the Dollar's direction heading into the weekend.
- Manufacturing PMI Falls Toward 52 — A sharper-than-expected industrial slowdown alongside a soft Services reading would make the week's economic picture look genuinely concerning and increase pressure on USD across major pairs.
- Oil Inventory Build Adds Inflation Concern — A surprise crude build could ease energy price pressures and reduce one of the remaining arguments for keeping rates higher, adding a subtle but real bearish layer to USD sentiment.
Check out the full calendar here: Followme Economic Calendar Tool
Follow Followme for the newest market updates


إخلاء المسؤولية: الآراء الواردة هنا تعبر فقط عن رأي الكاتب، ولا تمثل الموقف الرسمي لـ Followme. لا تتحمل Followme مسؤولية دقة أو اكتمال أو موثوقية المعلومات المُقدمة، ولا تتحمل مسؤولية أي إجراءات تُتخذ بناءً على المحتوى، ما لم يُنص على ذلك صراحةً كتابيًا.

